
Short-Term Investment Plans vs ULIPs: Which Is Better for Different Financial Goals?: Managing money is one of the best habits a person can develop in their lifetime.
Whatever your financial goals may be, whether it is to buy a new phone after 1 year, go on a vacation with the whole family in 3 years, or prepare for retirement years later, choosing the right place to park your hard-earned money matters a lot.
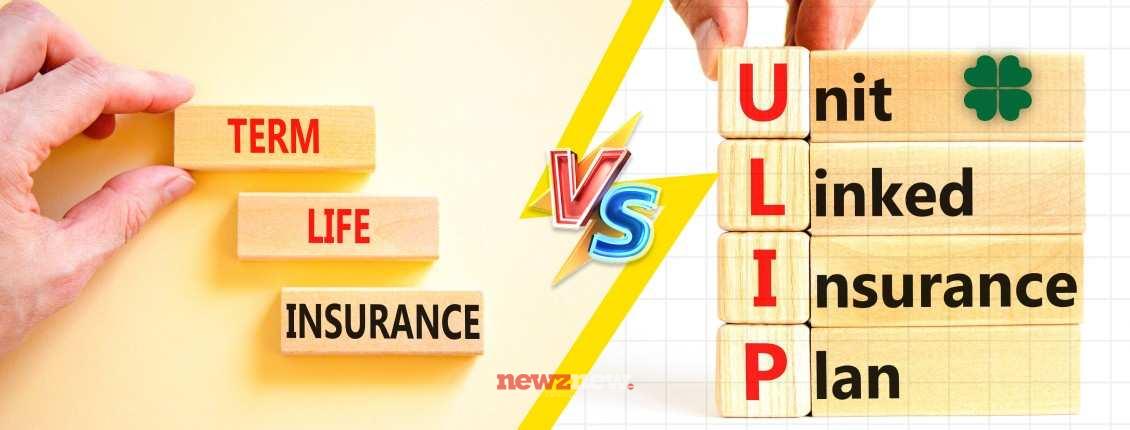
When you start exploring the options, you will see that there are several financial instruments that help you to reach your goals of accumulating money. Some of the most common financial tools in this space are a short term investment plan and a ULIP policy. Despite their similar aim, both these financial tools differ significantly in terms of their time frame and purpose. This plain-English article explains how both the financial tools work, the advantages they offer, and how one can make the right choice in their situation.
What is a Short-Term Investment Plan?
A short-term investment plan is a tool that helps to park your money for a shorter while, usually between a couple of months or even a year or two. The primary goal of a short-term investment plan is to ensure that your money is safe and can be easily accessed when you need it.
Some common examples of a short-term investment plan include bank FDs, RDs, short-duration mutual funds, and treasury bills, among others.
These instruments have the following advantages:
- High Liquidity: Short-term investment instruments offer easy liquidity and can be withdrawn at any given moment when an emergency comes up or your short-term financial goals near.
- Lower Risk: These instruments carry a lower risk profile and try to ensure that your money is secure.
- Predictable Timing: As the name suggests, these instruments help you set a deadline for when you need the money.
What is a ULIP policy?
A ULIP policy (Unit Linked Insurance Plan) is a unique offering by life insurance companies that aims to serve a dual purpose of ensuring that the family is financially secure if anything happens to the breadwinner of the family and growing money as an investment tool over a long period of time to build wealth.
When paying a premium towards a ULIP policy, some percentage of the amount goes towards giving the nominee life insurance cover, and the rest is invested in equity or debt funds or a combination of both as per the risk appetite of the buyer of the policy.
Since a ULIP policy is a market-linked instrument, it has been mandated by the regulator to have a 5-year lock-in period. This means that the money you invest in a ULIP policy cannot be withdrawn within 5 years.
Some of the major advantages of a ULIP policy are:
- Dual Purpose: A ULIP policy serves a dual purpose of providing life insurance cover to the nominees and building wealth over a long period of time.
- Switching Between Funds: ULIP policies offer the flexibility of switching the funds between equity and debt without any additional charges as the market demands.
- Compounding Benefits: A ULIP policy can compound wealth over time, helping to beat inflation effectively over a period of 10-15 years.
Taxation under the Income Tax Act, 2025
The taxation on these instruments plays a crucial role in determining the final returns of the investor. Here are the tax implications that apply to a ULIP policy and short-term investment instruments as per the Income Tax Act, 2025:
Premium Deductions
- Under Section 123 (read with Schedule XV) of the Income Tax Act, 2025, the premium paid towards a ULIP policy is eligible for deduction up to ₹1.5 lakh in a financial year. However, this deduction under Section 123 is generally available only if an individual chooses the old tax regime.
- Those who choose the New Tax Regime cannot claim any deduction for the premium paid towards a ULIP policy.
- Traditional forms of short-term investment instruments such as liquid funds and FDs are generally not eligible for deduction under Section 123.
Exemption on Maturity Proceeds and Death Benefits
- Death benefits received by a nominee under a ULIP policy are generally exempt from tax (Section 11 (read with Schedule II) of the Income Tax Act, 2025) regardless of the tax regime chosen.
- The maturity proceeds received on a ULIP policy may also receive favorable tax treatment under certain conditions (Section 11 (read with Schedule II) of the Income Tax Act, 2025) depending on the total amount of all the annual premiums being paid (should not exceed ₹2.5 lakh in a year, for policies issued under the recent guidelines). The maturity proceeds received in excess of the amount of annual premiums being paid may be treated as capital gains.
- Interest earned on short-term debt instruments is added to the income and taxed as per the applicable slab rates.
How to match the plans to real-life goals?
A ULIP policy and a short-term investment plan both have their own pros and cons and each fits best in different situations. The following paragraphs explain the best scenarios where each of these instruments fit:
Short-Term Goals (1-3 years)
If the monetary goal is within 1-3 years, then a short-term investment plan is the best bet. Let’s look at the following scenarios where a short-term investment plan can help:
- To build an emergency fund: In this situation, an individual needs a liquid fund that can be withdrawn in case of medical expenses or urgent housing repairs.
- To save for a down payment: If an individual wants to buy a car or house but the purchase is expected to happen in the next 2 years, then it is better not to expose this amount to the risks of the market.
- To save for an annual travel or tuition fee: The individual needs to make sure that he/she has enough money to meet regular expenses for the upcoming 12-36 months.
Long Term Goals (5-15+ years)
On the flip side, if the monetary goal is further away (5-15+ years), then a ULIP policy can help an individual achieve his/her financial goals with greater ease. Let’s take a look at the following long-term scenarios:
- To fund a child’s higher education: Higher education fees increase exponentially, and it is critical to have life insurance cover while growing the money in the long run to beat inflation.
- To save for retirement: An individual can build a good corpus over time to finance his/her retirement needs with the help of a ULIP policy while also enjoying life insurance cover.
- To build a legacy: Building a nest egg that can ensure the children’s financial security in case of unfortunate events.
What to consider before making a choice?
Before making a choice, it is very important that an individual considers the following aspects:
- Look at the lock-in period: It is essential to make sure that you do not put money in a ULIP policy that you will need for the next 2 years, as a ULIP policy has a 5-year lock-in period.
- Know the charges associated with a ULIP policy: A ULIP policy comes with several initial charges such as premium allocation charges and fund management charges in the early years of the policy that reduce the amount being invested.
- Assess your risk appetite: For people who are not very comfortable with the daily market volatility, ULIP equity funds are not the best bet. They could explore ULIP debt funds or other short-term investment instruments.
- Read the fine print: The premium rates, fund management options, mortality charges, surrender terms, and eligibility criteria differ for different insurers. It is critical to remember that all the benefits and terms listed in a ULIP policy are subject to individual insurer terms & conditions.
A ULIP policy and a short term investment plan both serve a unique purpose and complement each other to build a strong financial future. The short term instruments help you to ensure that your money is safe and can be withdrawn if an emergency arises, whereas a ULIP policy helps to build a legacy that can help your family in the long run. By putting aside the right amount of money towards the right instrument, you can build a financially secure future.
Disclaimer: This article is for informational & educational purposes only and should not be considered as financial or tax advice. Insurance products are subject to market risks and individual insurer terms & conditions. Tax benefits mentioned are as per the provisions of the Income Tax Act, 2025, and are dependent on the chosen tax regime and individual circumstances. Please consult a certified financial advisor or tax consultant before making any investment decisions.